Free equity review. No cost to apply. See what you qualify for

Business-purpose loans only. Proceeds must go to a business or investment use, and a signed business-purpose statement is required at closing. All loans are subject to appraisal and underwriting. Rates and fees are disclosed in writing before you commit to anything.

California · Business-Purpose Lending

Pull Cash From Your Equity & Leave Your First Mortgage Alone

A private cash-out 2nd mortgage gets you $50K to $5M+ against a California home or investment property for a business or investment purpose. The first loan you already have stays exactly where it is.

Check your eligibility
15+ years of private lending · $100M+ funded

“Private money costs more than a bank loan. We’ll show you the real numbers before you decide anything.”

Our standing promise on rates and fees
Homeowner shaking hands with a lender after reviewing loan terms
Decided in-house
Bright California home kitchen
Primary residence (business purpose)
Spanish-style California home with palm trees
Rental and investment property

Why borrowers pick a 2nd

3 Ways a Private Cash-Out 2nd Puts Your Equity to Work

Homeowner reviewing numbers with a lender01

1. Your first mortgage stays put

If you locked in a low rate on your first loan, refinancing it just to reach your equity can cost you more than it’s worth. A 2nd sits behind the loan you already have. Same payment on the first, same rate, same lender.

You borrow only the amount you need on top of it.
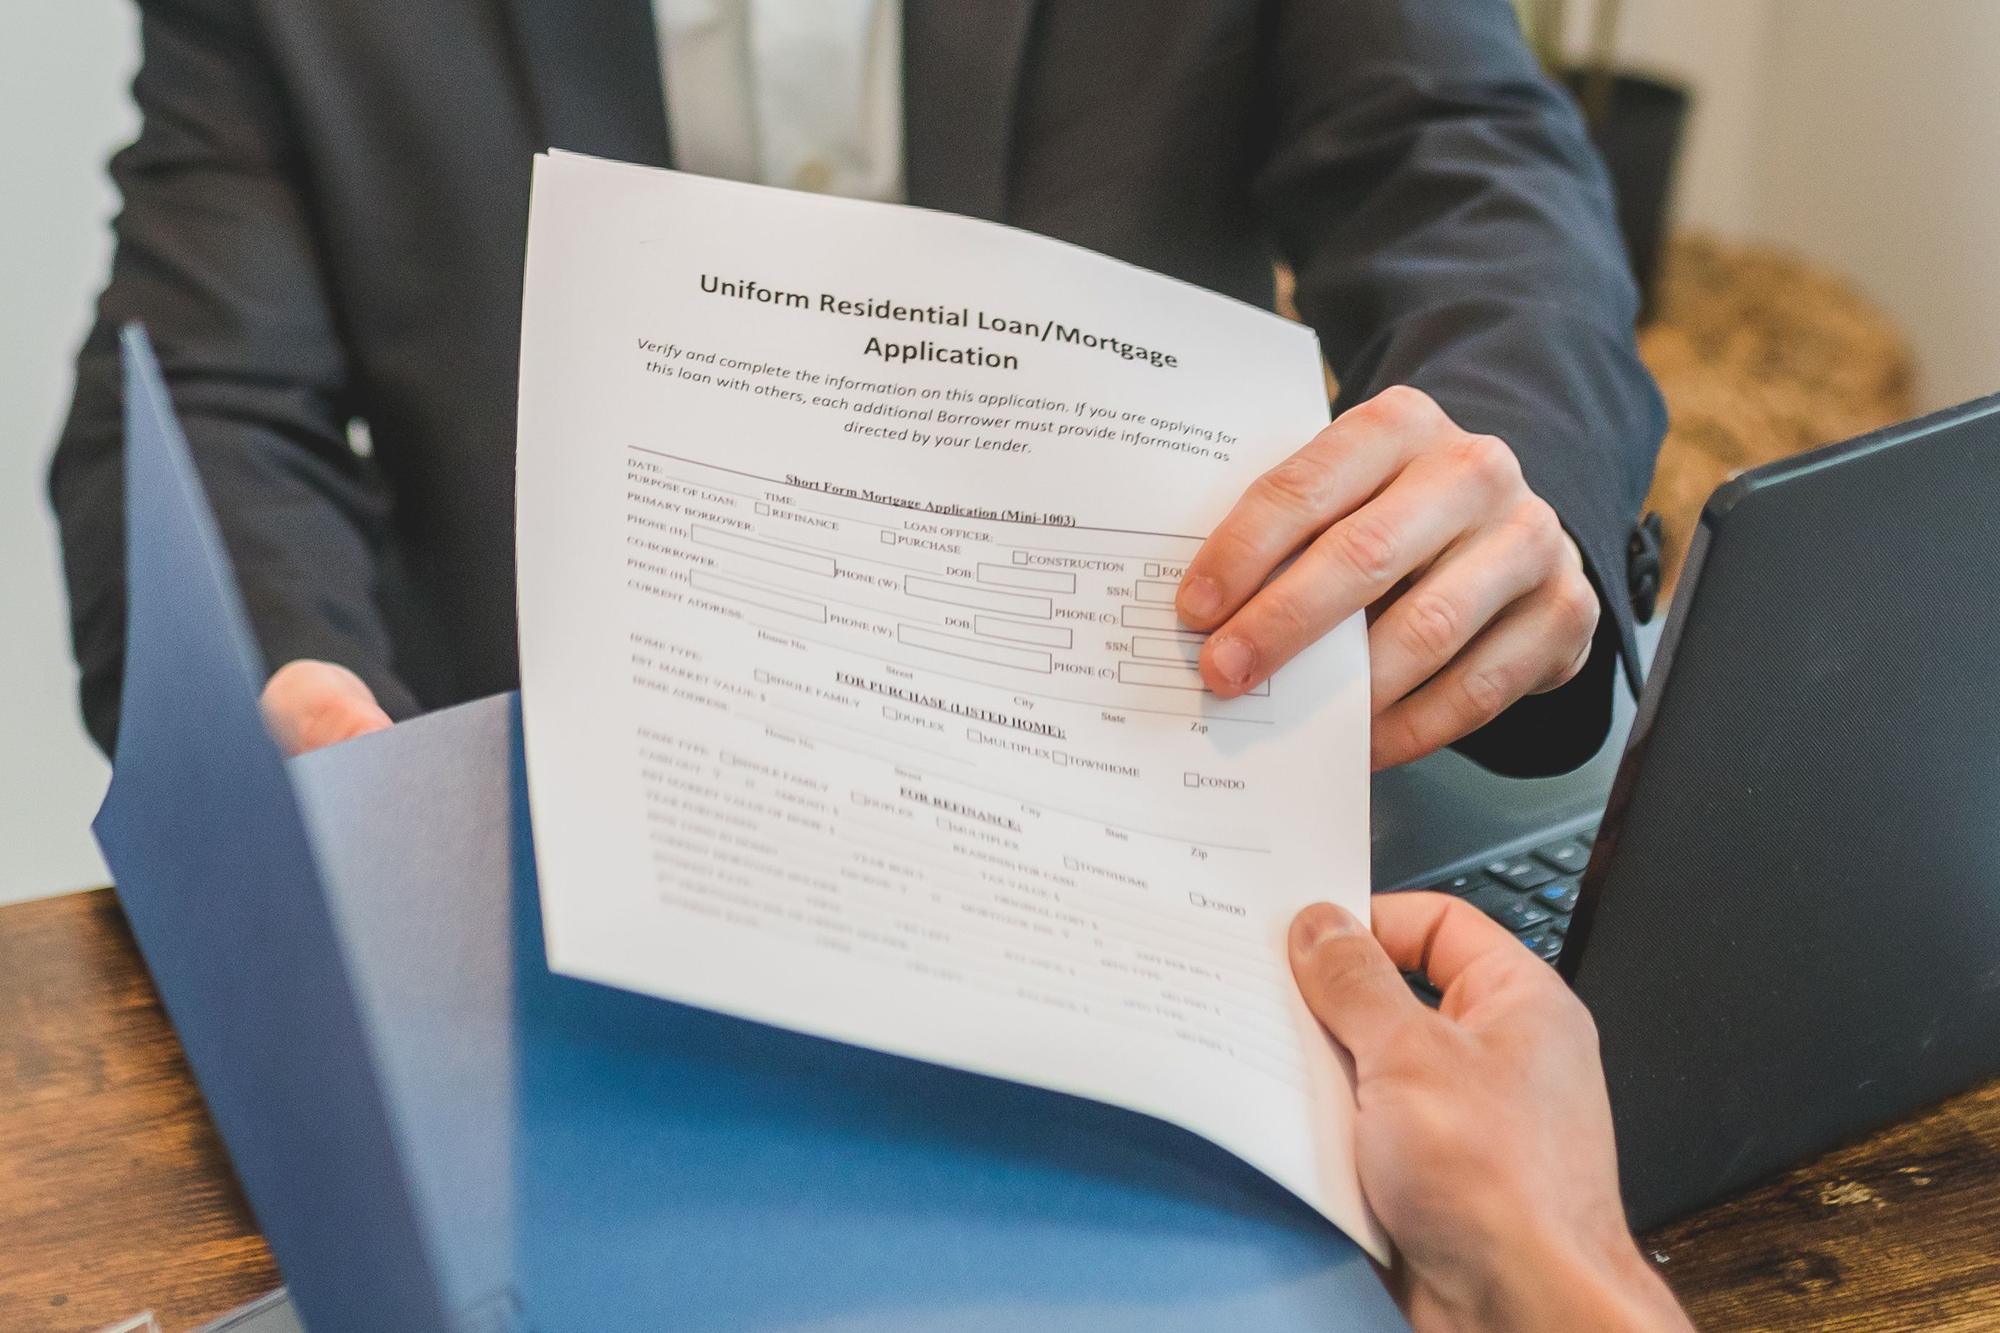
Loan application on a desk under review02

2. We look at the equity first

Self-employed, or a bank already said no? Our underwriting weighs your equity position, the property and your exit plan alongside credit. We do check credit. It just carries less weight here than at a bank.

And the decision is made by our own team, in-house.

Real estate investor at work03

3. It works on the home you live in

Plenty of private lenders won’t touch a primary residence. We will, when the money is going to a business or investment use: funding your company, buying another property, paying for a project.

Rentals and other investment properties qualify too. You sign a business-purpose statement at closing either way.

How a cash-out 2nd works

Your First Loan Plus the New 2nd Can Reach 65% of Value

We add up what you still owe on the first mortgage and the new 2nd. In California that combined total can go up to 65% of the property’s appraised value. Outside California the limit is 55%. Whatever room sits under that line is what you can borrow.

  • Loans start at $50K and run past $5M.
  • Your existing first mortgage isn’t touched, refinanced or paid off.
  • Rates and fees come to you in writing before you commit.

Estimate your room

Two numbers. Rough is fine.

First mortgagePossible 2nd65% line
$300,000

Estimated maximum 2nd at 65% combined LTV.

Estimate only, using the combined LTV limit for where the property is: 65% in California, 55% outside California. Not an offer or a commitment to lend. The actual amount depends on the appraisal and our underwriting.

[ What happens next ]

A Short Conversation. Then Real Numbers.

Lender on a phone call with a borrower
01

Tell us the situation

The property, roughly what’s owed and what the money is for. It costs nothing to ask.

Mortgage paperwork being reviewed
02

We review the equity

We look at what structures could work, including whether borrowing is even the right move for you.

Borrower signing loan documents
03

Options in writing

The realistic paths with real numbers attached. No pressure and no obligation to go ahead.

California DRE# 02037255 · NMLS# 233991

Private Cash-Out 2nd Mortgage

Loans from $50K Business purpose

Borrow against the equity in a California home or investment property and keep your first mortgage in place. Underwritten and decided in-house.

  • Up to 65% combined LTV in California, 55% elsewhere
  • Primary residence, rental, commercial or mixed-use
  • Rates and fees in writing before you commit

Choose your property:

How much do you need?

Pick your next step:

Prefer to talk it through? Call and tell us about the property.

Call (818) 937-9987
How it works

You tell us about the property, what’s owed and what the money is for. We review the equity and come back with options in writing. If it makes sense, the new 2nd records behind your existing first mortgage, which stays as it is.

Key features
  • Loan amounts from $50K to $5M+
  • First mortgage plus the new 2nd up to 65% of appraised value in California, 55% outside California
  • Primary residence (business purpose), rental, commercial and mixed-use property
  • Underwriting that weighs equity alongside credit
  • Backed by capital sources nationwide
Rates and fees

They vary by property and situation, and they’re disclosed in writing before any commitment. Private money costs more than a bank loan. That’s the trade for flexibility, and we’d rather you know it up front.

Who it’s for

Owners of California real estate with real equity, who need $50K or more for a business, an investment property or a project.

It probably isn’t a fit if you need to borrow past 65% of the property’s value counting your first mortgage (55% outside California), or if the money is for personal or household expenses.

What you won’t get from us
  • Application fees
  • Pressure to sign
  • Personal-use loans
  • A forced refinance of your 1st
  • Numbers you can’t see first
  • A decision made somewhere else
Licensing

Michael Daniel Investments, Inc. California Department of Real Estate DRE# 02037255 and NMLS# 233991. 417 Arden Ave, Suite 121A, Glendale, CA 91203.

Renovation underway at an investment property

One new loan

Get the Capital. Keep the Rate You Already Have.

Rates on first mortgages have moved a lot in the last few years. If yours is one worth keeping, a cash-out refinance means giving it up. A 2nd lets you hold onto it and borrow only what the project needs.

Use it to buy your next property, finish a rehab already underway or put money into your company.

Start my free review
Lender and homeowner shaking hands

Straight answers

“People ask us what the catch is. There isn’t one, but there is a rule we hold to: we make business-purpose loans only. If you need money for personal use, we’ll tell you we’re the wrong lender. If we can’t help, we’ll say so quickly, and where we can, we’ll point you toward what would.”

The Michael Daniel Investments lending teamGlendale, California

[ Loan details ]

Built Around Your Property

Owner-occupied California home

The home you live in

65%Max combined LTV in California (55% elsewhere)
$50K+Starting loan amount

Borrow against your own home when the money goes to a business or investment use, like funding your company or buying another property. A signed business-purpose statement is part of closing.

Spanish-style California rental home

Rentals and investment property

65%Max combined LTV in California (55% elsewhere)
$5M+Upper loan range

Pull equity out of a rental and leave the first loan alone. Investors use it for the next acquisition or to keep a rehab moving.

Commercial office building

Commercial and mixed-use

$50KMinimum
$5M+Upper loan range

Equity in a commercial or mixed-use building can fund the business that occupies it, or the next deal. Tell us about the property and we’ll look at what structure fits.

$100M+Funded over 15+ years of private lending

Is this the right loan for you?

May be a fit

You have real equity

You own a home or investment property in California, and the first mortgage leaves room under 65% of value.

May be a fit

The money has a business job

It’s going to a business, an investment property or a project.

May be a fit

You need $50K or more

Our loans start at $50K and go past $5M.

May be a fit

A bank turned you down

Self-employed, or turned down by a bank? We look at the equity first, and credit still counts.

Probably not a fit

You need more than 65%

If the first mortgage plus what you need goes past 65% of the property’s value (55% outside California), we can’t make that loan.

Probably not a fit

It’s for personal expenses

Household bills, vacations and other personal uses don’t qualify. We’ll tell you so on the first call.

Aerial view of a Southern California neighborhood

FAQs

What’s the catch?

There isn’t one, but there is a constraint worth being clear about. We make business-purpose loans only. Proceeds have to go to a business or investment use, not personal or household expenses, and you sign a business-purpose statement at closing.

Do you check credit?

Yes. Credit history is one factor alongside your equity position, the property’s condition and the exit strategy. Equity carries more weight here than at a bank. Any lender telling you credit doesn’t matter isn’t being straight with you.

What are your rates and fees?

They vary by product and situation, and they’re disclosed in writing before any commitment. Private money costs more than a bank loan. We’ll show you the real numbers before you decide anything.

Can I borrow against the home I live in?

Yes, when the loan has a business or investment purpose. Many private lenders won’t lend on a primary residence at all. We do, with a signed business-purpose statement at closing.

How much can I borrow?

From $50K to $5M+. Your first mortgage plus the new 2nd can total up to 65% of the property’s appraised value in California, or 55% if the property is outside California. The calculator above gives you a rough idea; the appraisal and underwriting set the real number.

What if I don’t qualify?

We’ll tell you, and where we can we’ll point you toward what would help. If you’re facing foreclosure, free counseling is available from a HUD-approved housing counselor at hud.gov/findacounselor or (888) 995-HOPE.

Have Equity to Work With?

Join the borrowers behind $100M+ in private loans funded. Tell us about the property and we’ll show you the real numbers. No cost, no obligation.

Start the conversation or call (818) 937-9987
California homes from above

Business-purpose loans only. Loan proceeds must be used for a business or investment purpose and may not be used for personal, family or household purposes. A signed business-purpose statement is required at closing. All loans are subject to property appraisal, underwriting review and approval. Rates, fees and terms vary by property and borrower situation and are disclosed in writing before you commit. The 65% (California) and 55% (outside California) figures are maximum combined loan-to-value, counting all existing liens. Calculator results are estimates only and are not an offer or commitment to lend.

If you’re facing foreclosure, free counseling is available from a HUD-approved housing counselor at hud.gov/findacounselor or (888) 995-HOPE.

Call Check eligibility