
A Private Cash-Out 2nd Mortgage,
Built Around Your Temecula Property.
Check Your Eligibility ↓
A private cash-out 2nd mortgage lets Temecula property owners tap their equity for a business or investment purpose, without refinancing an existing first mortgage, subject to our underwriting. Headquartered in Glendale, we underwrite Riverside County deals directly.
By submitting you agree to be contacted by phone, text, or email about your inquiry. Consent is not a condition of obtaining a loan. See our Privacy Policy.
Know Before You Call
Do You Qualify? What to Expect
Quick Self-Check
Is This the Right Loan for You?
- You own a home or investment property in California with real equity in it.
- The money is going to a business, an investment property or a project.
- You need $50K or more.
- You need to borrow more than 65% of the property’s value, counting your first mortgage.
- The money is for personal or household expenses.
How It Works
Equity-Based, Not Credit-Score-Gated
Who It’s For
Homeowners and Investors
Plenty of private lenders won’t touch a primary residence. We lend on the home you live in when the loan has a business purpose, and on investment property too.
The Temecula Market
Newer, Larger-Lot Growth South of the Inland Empire’s Core
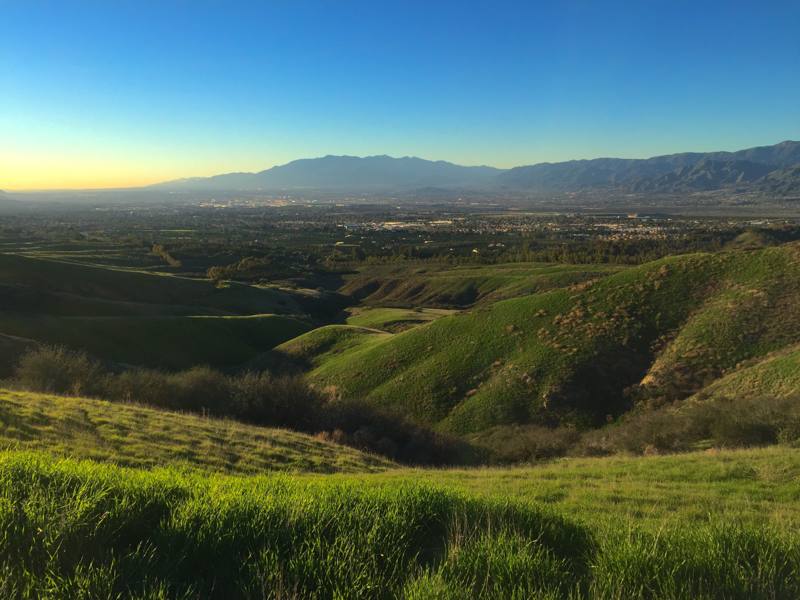
Temecula’s growth has largely been newer, master-planned communities with larger average lot sizes, plus properties adjacent to the wine country south of the city that can include acreage, vineyards, or outbuildings. That’s a different profile from denser, older Inland Empire cities like Riverside or San Bernardino, and it changes what an appraisal actually needs to account for.
We underwrite Riverside County deals, including Temecula, directly out of our Glendale office. When a property includes acreage or agricultural improvements, we factor those into the appraised equity rather than defaulting to a standard suburban-lot comp.
Straight Answers
Questions Temecula Homeowners Ask
Do you actually work in Temecula, or is this a national call center?
We’re headquartered in Glendale and underwrite Riverside County deals, including Temecula, directly — not through an out-of-state call center. A larger-lot property near the wine country and a home in a newer Temecula tract get evaluated differently, and that’s part of how we structure a file. We underwrite Temecula-area deals in-house.
My property includes agricultural or vineyard acreage — does that affect what you can lend?
Yes, in a good way for sizing the loan. Acreage, vineyards, and outbuildings factor into the appraised equity alongside the primary residence. We look at the full property rather than treating it like a standard suburban lot.
What’s the catch?
There isn’t one, but there is a constraint worth being clear about: MDI makes business-purpose loans only. Proceeds have to be used for a business or investment purpose, not personal or household expenses, and a signed business-purpose statement is required at closing. If you need money for personal use, we’re not the right lender.
Do you check credit?
Yes. Credit history is one factor alongside your equity position, the property’s condition, and the exit strategy. Equity carries more weight here than at a bank, but any lender telling you credit is irrelevant is not being straight with you.
What are your rates and fees?
They vary by product and situation, and they’re disclosed in writing before any commitment. Private money costs more than a bank loan. That’s the trade for speed and flexibility. We’ll show you the real numbers before you decide anything.
What if I don’t qualify?
We’ll tell you quickly, and where we can we’ll point you toward what would actually help. If you’re facing foreclosure, free counseling is available from a HUD-approved housing counselor at hud.gov/findacounselor or (888) 995-HOPE.
The Process
What Happens Next
Have Equity in Your Temecula Property?
No cost to apply. We’ll show you the real numbers.
Start the Conversation → or call (818) 937-9987Locations: Riverside County, California
Michael Daniel Investments, Inc.
417 Arden Ave, Suite 121A, Glendale, CA 91203
California Department of Real Estate DRE# 02037255 and NMLS# 233991.